 Skip to content
How to Estimate Car Accident Compensation in Opelousas, Louisiana
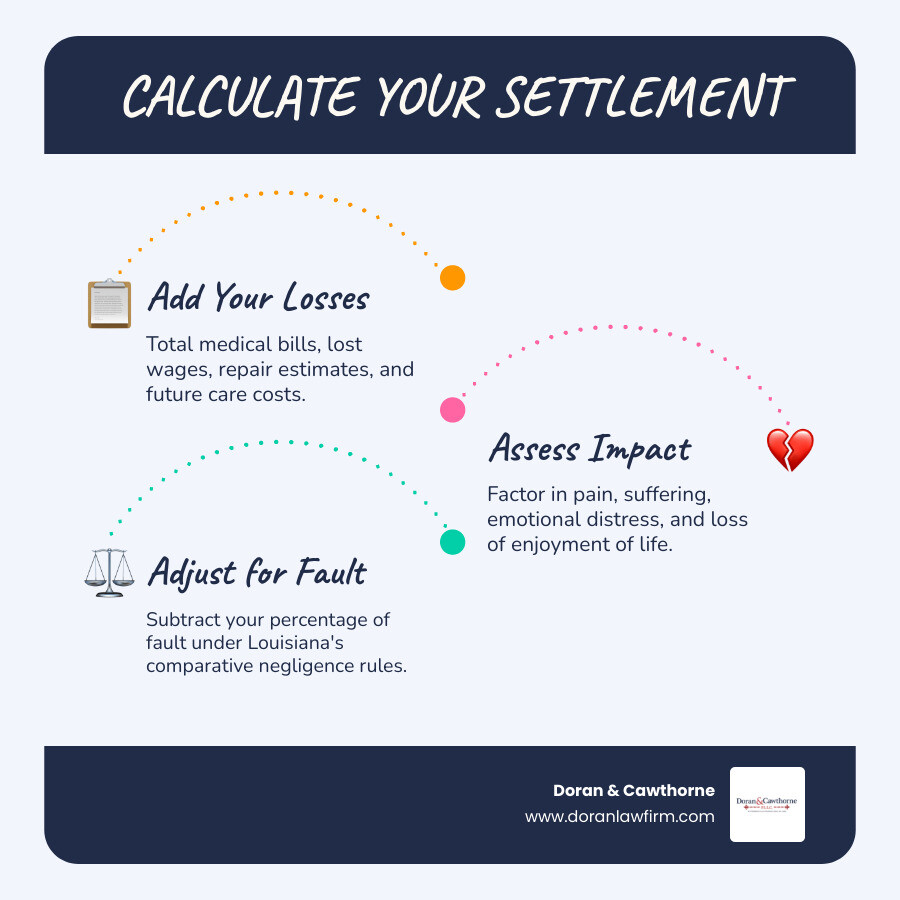
Call Doran & Cawthorne before accepting an insurer’s settlement. To calculate Opelousas Louisiana car accident compensation, combine your emergency medical bills, ongoing treatment costs, lost wages, and property damage repairs. Next, evaluate non-economic impacts like physical pain and adjust for any comparative fault before negotiating with insurers.
Your insurance claim often involves much more than the baseline cost of repairing your bumper. Louisiana law provides critical consumer protections, including your right to select any local collision repair facility. Securing fair car accident compensation in Opelousas, Louisiana also requires proving all crash-related losses caused by a negligent motorist.
By Pride Doran. I am a trial lawyer with over twenty years of courtroom experience handling serious automobile and commercial trucking claims. That background shapes this guide to recovering full financial damages across St. Landry Parish. My firm has recovered substantial six-figure settlements by meticulously documenting every loss before negotiations begin.
According to parish crash statistics compiled by the Louisiana DOTD crash report database, 823 people were injured in St. Landry Parish crashes in 2023. These collisions frequently leave motorists facing steep out-of-pocket medical debt, missed work shifts, and stressful vehicle repair disputes.
How Do You Calculate Opelousas Louisiana Car Accident Compensation After a Crash?
To calculate your total payout, combine all quantifiable economic losses with general non-economic damages, then reduce the sum by your percentage of fault under Louisiana pure comparative negligence rules. Medical records, employer earnings statements, and certified body shop invoices establish the financial evidence necessary to demand full recovery from insurers.
Calculating Economic Damages and Property Repairs
Economic damages cover your direct, out-of-pocket financial losses resulting from a collision. These losses include emergency room care, diagnostic imaging, physical therapy sessions, future surgery costs, and lost weekly income. They also encompass vehicle repair estimates and prescription medication expenses.
Maintaining an organized file of receipts, hospital billing statements, and employer wage verification letters prevents insurance adjusters from minimizing your actual expenses. Proving future medical needs often requires written opinions from treating physicians who understand the long-term prognosis of your injuries.
Determining Non-Economic Payouts for Serious Injuries
Non-economic damages compensate victims for the subjective, personal toll of an automobile crash. These damages address acute physical pain, emotional distress, post-traumatic anxiety, sleep disruption, and the loss of enjoyment of daily life. They also account for permanent scarring, disfigurement, or physical disability.
Because non-economic losses lack fixed price tags, insurance carriers regularly try to undervalue them during early settlement discussions. Thorough treatment notes, mental health records, and daily pain journals help demonstrate the true severity of your suffering. Our firm helps crash victims accurately value their Opelousas car accident compensation claims.
What Are Your Legal Rights for Vehicle Repairs and Total Loss Claims in Louisiana?
Louisiana law grants vehicle owners absolute authority over their property damage repairs following a motor vehicle collision. Under LA. R.S. 22:1892(D)(1), insurance adjusters cannot mandate specific repair facilities or penalize you for choosing an independent body shop. Furthermore, state regulations declare vehicles a total loss when repair estimates reach seventy-five percent of market value.
Understanding these statutory protections shields you from adjuster pressure and ensures your vehicle is repaired using safe, approved components.
Selecting a Body Shop and Managing Opelousas Louisiana Car Accident Compensation
You have the right to choose any licensed collision repair center in St. Landry Parish. Insurers are legally prohibited from delaying your claim or reducing payments because you selected an independent local facility instead of their preferred direct-repair vendor. Local body shops work directly with you to ensure thorough structural assessments.
Before authorizing work, obtain a detailed written estimate outlining anticipated labor rates, frame alignment procedures, and paint refinishing charges. If an adjuster disputes local market labor rates, written documentation from reputable local mechanics helps enforce your rights.
Understanding OEM Parts, Non-OEM Disclosures, and the 75 Percent Total Loss Rule
Louisiana statutes require insurance companies to provide written disclosures whenever repair estimates specify aftermarket or non-Original Equipment Manufacturer (non-OEM) components. These replacement parts must match factory specifications in terms of structural integrity, corrosion resistance, and safety.
When structural frame damage or mechanical repair costs equal or exceed 75% of your car’s actual cash value prior to the crash, Louisiana law requires the vehicle to be deemed a total loss. In total-loss scenarios, insurers must pay the full fair market value plus applicable state and local sales taxes.
| Part Type | Source & Quality | Written Disclosure Required? |
|---|---|---|
| OEM (Original Equipment) | Built directly by vehicle manufacturer | No (Standard factory fit) |
| Non-OEM Aftermarket | Built by third-party suppliers | Yes (Mandatory written notice) |
| Recycled / Salvage | Sourced from undamaged donor vehicles | Yes (Must state recycled status) |
Who Pays for Your Rental Car and Repair Invoices During an Insurance Claim?
The at-fault driver’s insurance carrier must cover your temporary replacement transportation while your vehicle undergoes active body shop repairs. If you carry rental reimbursement under your own policy, your insurer can provide immediate coverage and seek reimbursement through subrogation from the liable driver’s insurer.
Unreasonable insurer delays require the at-fault carrier to extend car rental authorizations so you do not lose reliable transportation.
Recovering Rental Reimbursement from At-Fault Insurance Carriers
When another driver causes a collision, their liability coverage includes providing a comparable rental vehicle throughout the reasonable duration of repairs. If the insurer stalls vehicle inspections or delays approving initial estimates, they remain financially responsible for the resulting additional rental days.
Always monitor rental daily limits and policy caps closely. Keeping copies of all rental agreements, mileage logs, and fuel receipts ensures complete reimbursement if billing disputes arise later with claims adjusters.
Resolving Direct Pay and Disputed Invoices with Auto Insurers
Collision repairs often reveal hidden structural, electrical, or suspension damage once technicians disassemble the bumper and body panels. When technicians identify previously unseen damage, the body shop submits a supplemental repair invoice directly to the insurance adjuster for approval.
Insurers routinely dispatch field appraisers to inspect supplemental damage before approving direct payment to the facility. Establishing clear communication between your repair technician and the insurance carrier prevents unnecessary delays in vehicle turnaround times.
What Happens if You Disagree with an Insurance Settlement Offer in Opelousas?
If you dispute an inadequate insurance settlement offer, you can invoke your policy appraisal clause, submit a detailed formal demand letter, or file a civil lawsuit in parish court. Louisiana law imposes severe statutory penalties on insurance companies that arbitrarily refuse to settle valid claims in good faith.
Adjusters frequently present low initial offers, hoping unrepresented claimants accept fast checks before discovering the full extent of their medical needs.
Maximizing Your Opelousas Louisiana Car Accident Compensation Against Bad-Faith Adjusters
Insurance carriers doing business in Louisiana must handle claims fairly, transparently, and promptly. You can learn how long insurance has to pay a claim in Louisiana to identify improper stalling tactics by claims handlers.
Under LA. R.S. 22:1973, insurers that fail to pay claims within designated statutory deadlines after receiving satisfactory written proof of loss face substantial penalties and mandatory attorney fee awards. Proving bad faith requires presenting clear documentation of your losses alongside proof that the adjuster lacked a valid factual or legal defense for denying or delaying payment.
Filing a Lawsuit in St. Landry Parish Civil Court
When pre-litigation negotiations stall, filing a civil petition in the 27th Judicial District Court in Opelousas protects your legal rights. Louisiana maintains strict civil filing deadlines, making prompt legal action essential.
Litigation allows your attorney to conduct formal discovery, issue subpoenas, inspect traffic camera footage, and depose at-fault motorists under oath. Presenting organized evidence before a local judge or jury creates the necessary leverage to secure full and fair financial recovery.
Frequently Asked Questions About Car Accident Claims in Opelousas
Can My Insurance Premium Increase if the Crash Was Not My Fault?
No, Louisiana law expressly prohibits auto insurance companies from raising your premium rates or adding surcharges solely because you filed a non-at-fault claim. Premium rate hikes generally apply only when you bear primary legal responsibility for causing a collision.
What Specific Questions Should I Ask an Opelousas Repair Shop Before Work Begins?
Ask whether their body technicians maintain I-CAR or ASE certifications and if the shop offers written lifetime warranties on structural repairs and paintwork. You should also confirm how they handle supplemental insurer estimates and whether they intend to install OEM, non-OEM, or recycled salvage parts.
How Long Does an Insurance Company Have to Pay a Claim in Louisiana?
Under state law, an insurance carrier generally has 30 days to pay a property damage or bodily injury claim after receiving satisfactory written proof of loss and reaching an agreement. Unjustified delays beyond this statutory window expose insurers to bad-faith penalties.
Protecting Your Rights After a Crash
Securing complete compensation requires documenting every expense, demanding fair vehicle repair standards, and resisting bad-faith insurer delay tactics. Our legal team at Doran & Cawthorne helps injured drivers navigate complex insurance disputes across St. Landry Parish. Contact Pride Doran.
Share this Blog

When You Need Real Talk & Results™
Louisiana Personal Injury Attorneys Committed to Advocating on Your Behalf

